Five million industrial robots were operating in factories worldwide at the end of 2025, according to the International Federation of Robotics. The new World Robotics report says more than 600,000 units were installed during the year, an 11% increase. Behind that round-number milestone is a market developing at sharply different speeds.
China installed 354,000 robots, representing 59% of the global total. For manufacturers in Europe and North America, the significance is not simply the number of machines. It is the speed at which automation demand, integration experience and local supply chains are accumulating in one market.
In this article
What the five-million figure actually counts
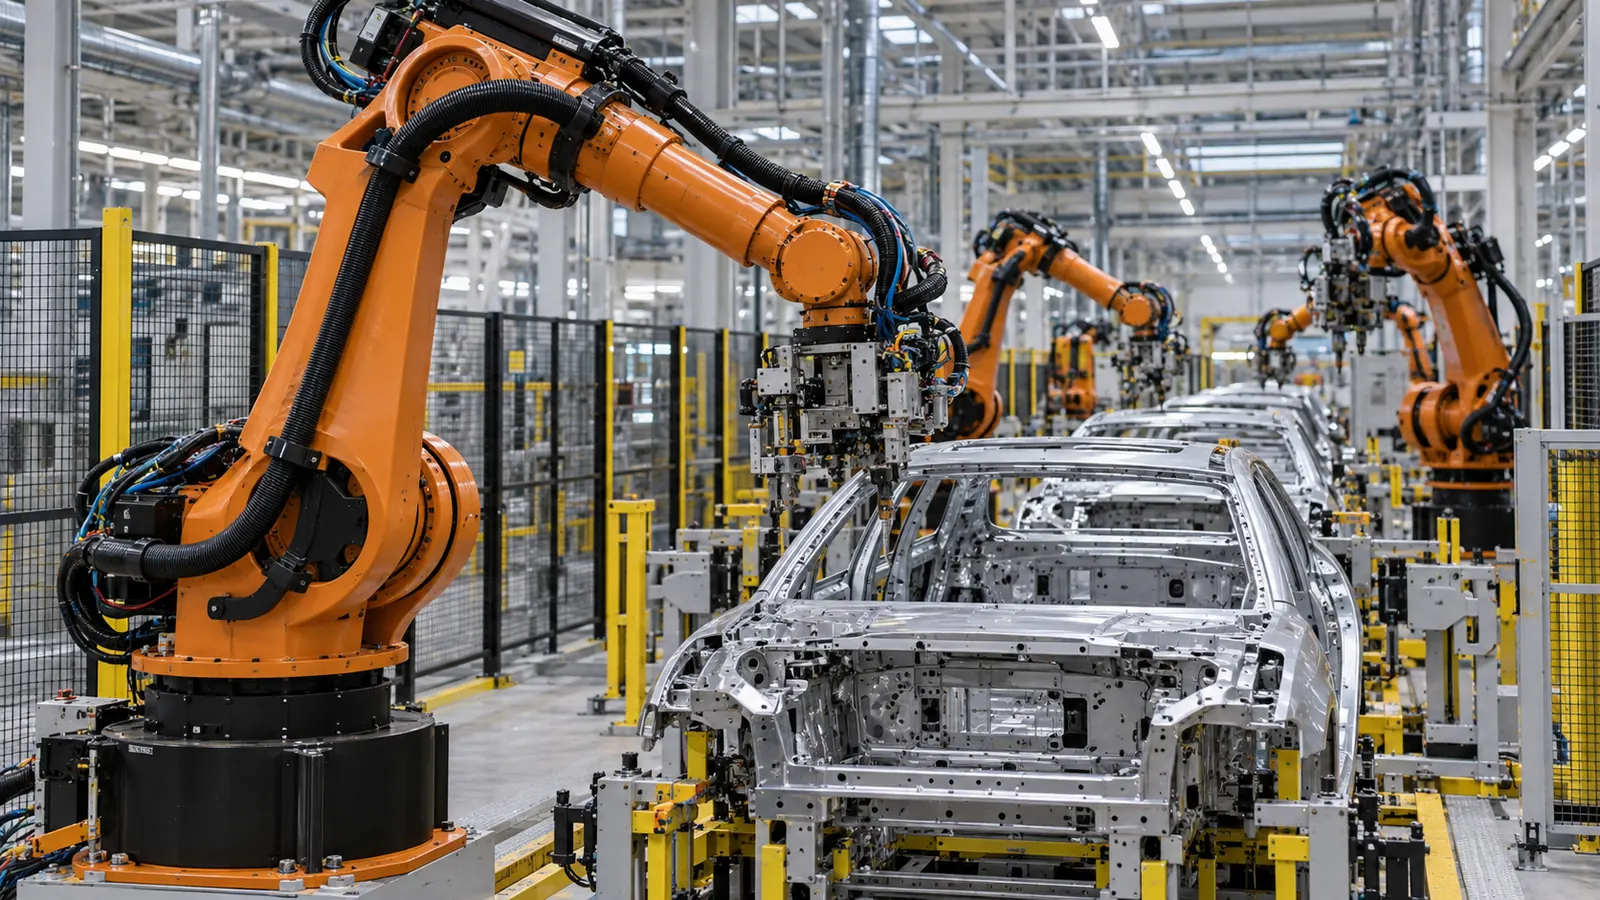
The IFR measure refers to the operational stock of industrial robots. These are primarily programmable machines that weld, paint, assemble, palletize or handle material inside defined industrial processes. Humanoid robots, household devices and many simple automated machines do not automatically belong to the same category.
The milestone therefore does not prove the sudden arrival of human-like AI workers. It shows continued growth in established factory robotics and a much larger installed base. Cameras, machine learning and more adaptable software are increasingly being added to that base, but most of the fleet still performs specialized work in structured environments.
China installs more than every second new robot
China’s share is the standout figure. Its 354,000 installations accounted for 59% of the world market and represented a 20% annual increase, according to the IFR. The scale is not merely evidence of lower-cost hardware. It also creates a large domestic environment in which integrators, component suppliers and factory operators can learn.
That can become a reinforcing cycle. More deployments produce more operating experience and trained staff, reduce integration costs and strengthen local supply networks. At the same time, a unit count says little about whether individual systems are used efficiently or whether the investments generate an adequate return.
The United States moves ahead of Japan in annual installations
The United States moved ahead of Japan in annual robot installations in 2025. Japan nevertheless remains a leading exporter and accounts for about 30% of global robot production, the IFR says. The comparison illustrates two different roles: one country can be a rapidly expanding customer market while another maintains a powerful manufacturing and export base.
US demand is supported by new semiconductor, battery and logistics investment. The next questions are how much of the equipment is produced domestically and whether smaller manufacturers can adopt it economically. A heavily automated greenfield plant and a mid-sized supplier face very different technical and financial barriers.
Germany remains Europe’s largest market but loses momentum
Germany is still Europe’s most important robotics market, yet the IFR recorded an 8% decline in new installations. One weaker year does not establish a structural reversal. Combined with high financing and energy costs and uncertainty in the automotive sector, however, it is a warning sign.
Germany’s strength lies in mechanical engineering, applications knowledge and industrial integration. The risk is that modernization projects are delayed while other markets invest at scale. That would affect more than the machine count. Practical expertise in new robot generations, machine vision and AI-assisted process control could also develop more slowly.
Robot stock is not the same as productivity
An installed-base figure measures units, not utilization or economic output. Two identical robots can deliver very different results. One may run continuously in a stable process; another may spend long periods idle because of product variation, component shortages or difficult programming.
A useful assessment therefore needs operating hours, scrap rates, changeover time, availability, energy consumption and cost per finished part. Safety and workforce skills also matter. High robot density can support competitiveness, but it cannot compensate for a poorly designed process.
Why conventional arms still matter during the physical-AI boom
Humanoid robots attract attention because developers promise machines that can enter spaces designed for people. The IFR milestone is a reminder that companies still buy purpose-built systems for most real production work. A fixed arm is often faster, less expensive and more robust when the task is predictable.
Physical AI can nevertheless change these established machines. Better perception and learning-based control can help them deal with unordered parts, frequent product changes or less precisely prepared workstations. Much of the economic progress may therefore look unglamorous: a conventional arm handles more variation rather than a general-purpose humanoid appearing overnight.
Alpha Bionic view: Europe must scale integration
The main lesson from five million robots is not that machines are simply replacing people. It is that automation has become an infrastructure question. China is building that infrastructure at exceptional speed, while Germany’s new installations recently lost momentum.
European companies therefore need more than eye-catching robots. They need standardized integration packages, available technical talent and financing that makes adoption practical for mid-sized manufacturers. The next meaningful comparison should ask not only how many robots were installed, but how quickly factories can configure them for new products and how much measurable value they create.
Sources
- International Federation of Robotics: Five Million Robots Now Operate in Factories Globally, September 24, 2026
- Business Wire China: World Robotics 2026 data, September 24, 2026
- The Robotics Media: IFR World Robotics 2026, September 25, 2026